The EU-India Trade Deal Didn't Buy India a CBAM Exemption: What Steel and Aluminium Importers Should Plan For
The EU-India Trade Deal Didn't Buy India a CBAM Exemption
When the EU and India concluded their free trade agreement on 27 January 2026, tariffs on the vast majority of bilateral trade were set to fall. Some importers read that as a signal that Indian steel and aluminium might escape the Carbon Border Adjustment Mechanism. They will not.
What the agreement actually says about CBAM
The Commission was explicit: "There is no commitment on the part of the EU to change our obligations with regard to the carbon border adjustment mechanism (CBAM)," and India is treated the same as every other trading partner. Argus Media reports that the deal does allow a "technical dialogue" on CBAM implementation, alongside a climate chapter and roughly €500 million in EU support over two years for Indian greenhouse gas mitigation.
Formal adoption also takes time: legal review, translation and parliamentary consent are expected to run for about a year. CBAM's definitive period, meanwhile, is already running.
Why steel is the exposure
Analysis from Ideas for India notes that iron and steel account for the overwhelming majority of India's CBAM-exposed trade. The default emission intensity for steel is 4.32 tonnes of CO₂ per tonne, while the Indian national average is reported to be roughly half of that default.
That gap is the commercial story. If your supplier cannot provide verified, installation-level data, you are pricing against a default value that overstates the real emissions, and you pay for the difference.
The small-supplier problem
The same analysis notes that micro, small and medium enterprises account for around 40% of Indian steel production, and that monitoring, reporting and verification costs can be prohibitive for them. For importers this means supplier readiness will be uneven. Some Indian mills will hand you verified data; others will not, and your default-value exposure follows the supplier, not the trade deal.
What to do now
- Segment your Indian suppliers by data readiness. Separate those with a monitoring plan and a verifier lined up from those still on defaults.
- Quantify the default-value gap. Compare the default intensity to any supplier-reported figure to see what verified data would be worth per tonne.
- Ask about carbon pricing at origin. India's own carbon market scheme is expected to launch in 2026 for energy-intensive sectors, per the EEAS summary of EU-India CBAM cooperation. Any carbon price actually paid may become deductible, subject to the implementing rules.
- Do not budget on tariff savings offsetting CBAM. They are separate mechanisms with separate cash flows.
- Watch the technical dialogue. It may improve procedures for Indian producers, but it is not an exemption.
Bottom line
The India deal changes tariffs, not carbon obligations. Treat Indian steel and aluminium like any other CBAM-covered import: verify the data, model the default-value gap, and keep the compliance timeline separate from the trade-deal timeline.
Related reading
Who Can Actually Accredit Your Supplier's Verifier? Reading the Commission's CBAM Accreditation State-of-Play
The Commission's 25 September accreditation update shows 24 national bodies on board, 15 ready and only 5 taking third-country applications. What that means for suppliers outside the EU and the importers who depend on them.
Norway and Iceland Are Joining CBAM: What the EEA Joint Committee Decisions Change for Importers
On 25 September 2026 the EEA Joint Committee adopted two decisions bringing CBAM to Norway and Iceland. Adoption is not entry into force, though. Here is what is decided, what is pending, and what to watch.
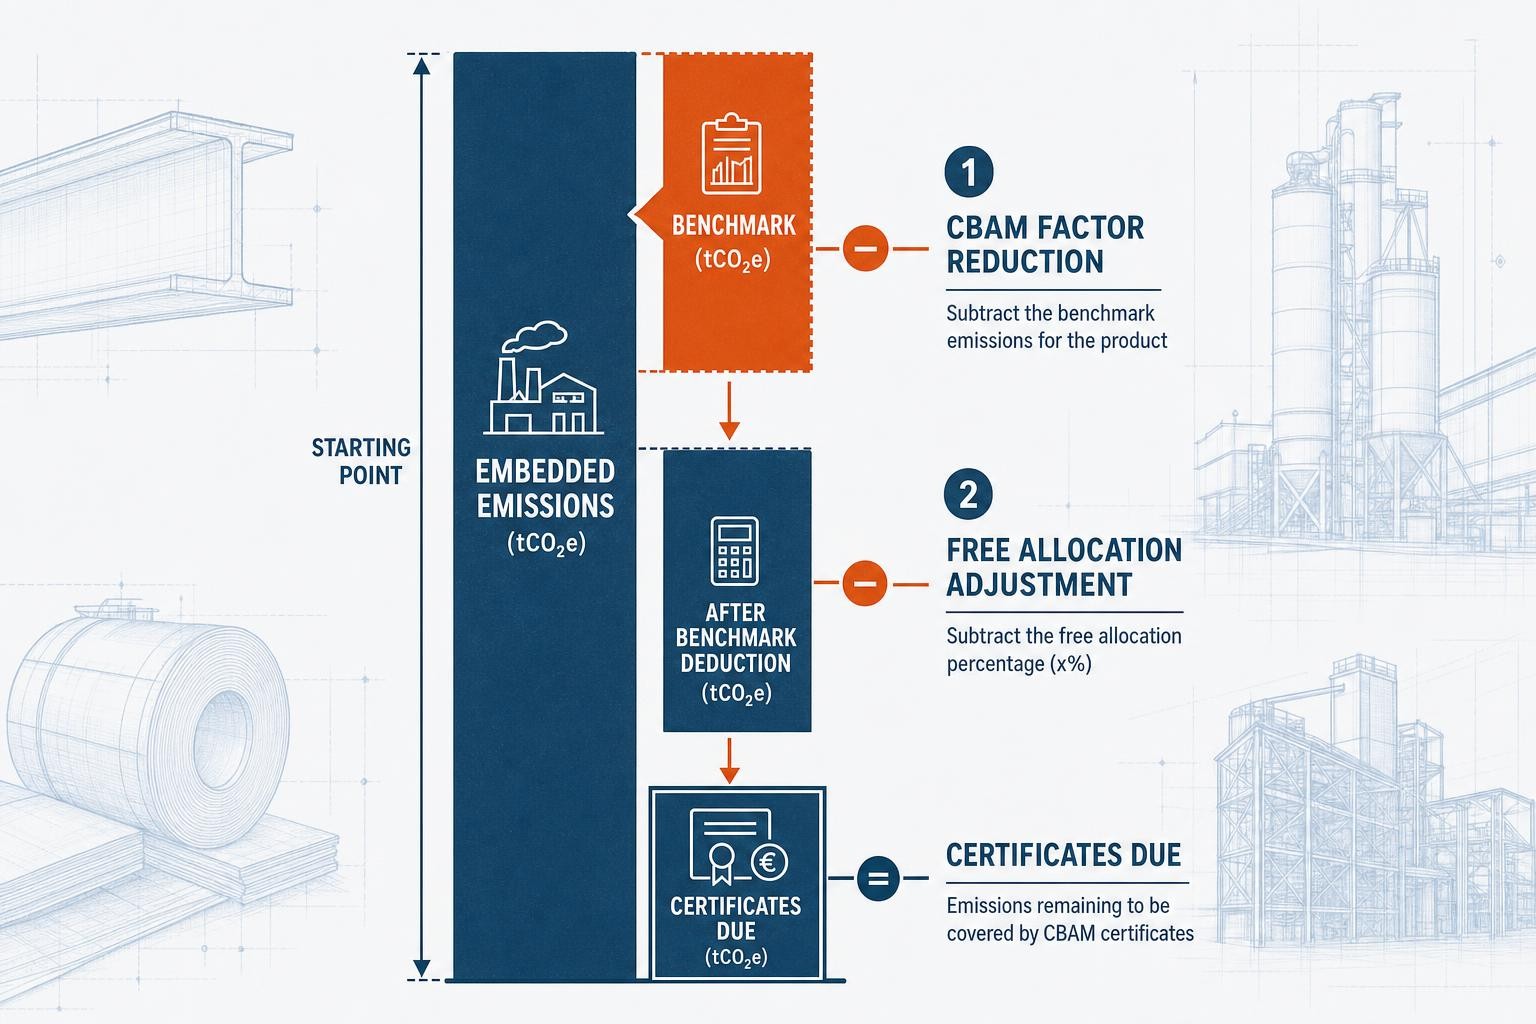
The Two Reductions Nobody Tells You About: CBAM Certificates, the CBAM Factor, and the Free Allocation Adjustment
Your CBAM certificate bill is not simply 2.5% of embedded emissions. There are two distinct reductions - the CBAM factor and the SEFA free allocation adjustment - and conflating them changes the cash number.